Your auditor asks for documentation supporting an asset disposal from two years ago. You open the spreadsheet, only to find that several people have edited it since the last close. The disposal is recorded in one file, depreciation is calculated in another, and nobody is certain which version contains the final numbers.
Fixed asset management becomes harder as asset portfolios, locations, reporting requirements, and depreciation schedules grow.
The most common fixed asset management challenges are maintaining accurate asset records, managing depreciation across multiple books, and keeping tax depreciation and reporting requirements organized. Addressing these challenges requires consistent processes, reliable asset data, regular reconciliation, and tools that can support the accounting lifecycle of each asset.
This guide explains where these problems come from and the fixed asset management best practices finance teams can use to address them.
What Makes Fixed Asset Management Difficult?
Fixed asset management involves more than maintaining a list of equipment, buildings, vehicles, furniture, or other capital assets.
Finance teams need accurate information throughout the asset lifecycle, from acquisition and placed-in-service through depreciation, transfers, adjustments, physical inventory, and eventual disposal.
- Asset acquisitions and placed-in-service dates
- Cost and depreciable basis
- Asset classifications and useful lives
- Depreciation methods and conventions
- Book and tax depreciation
- Location and department changes
- Transfers, adjustments, and disposals
- Physical inventory
- General ledger reconciliation
- Financial and tax reporting
Each activity affects the records that follow it. An incorrect placed-in-service date, for example, can affect depreciation calculations and subsequent reporting. A disposal that is never recorded can leave an asset on the books after it has left the organization.
The challenge grows when these activities are managed through disconnected spreadsheets, manual calculations, or separate systems.
Challenge #1: Maintaining Accurate Fixed Asset Records
Accurate fixed asset data is the foundation of depreciation, reporting, reconciliation, and audit support. When the underlying asset record is incomplete or inconsistent, those problems can flow into downstream accounting processes.
Why Spreadsheet-Based Asset Records Become Difficult to Manage
Spreadsheets can work for straightforward asset portfolios, but maintaining control becomes more difficult as the fixed asset management process grows more complex.
One person may update an acquisition while another records a transfer in a separate file. A disposal might be reflected in the general ledger without being removed from the fixed asset schedule. Changes to formulas or columns can also make it harder to determine whether calculations remain consistent across the entire workbook.
- Multiple versions of the same asset file
- Manual formulas that require ongoing review
- Separate tabs or files for different schedules
- Inconsistent asset classifications
- Missing acquisition or disposal information
- Changes that are not reflected across every relevant record
- Difficulty determining who changed information and why
These issues are particularly important when several people participate in the accounting process or when asset information needs to be reproduced months or years later.
How Inaccurate Records Affect Accounting
Poor fixed asset data can surface in several ways. A disposed asset may remain on the books because its retirement was never recorded. These records are sometimes described as ghost assets because the accounting records continue to show assets that are no longer in service or cannot be located.
The opposite can happen as well. An asset may exist physically but be missing from the accounting record or contain incomplete cost, location, or depreciation information.
- Depreciation calculated from incorrect inputs
- Differences between fixed asset records and the general ledger
- Difficulty reconciling physical inventory
- Missing support for transfers and disposals
- Additional investigation during close
- More work when preparing information for auditors or tax professionals
The longer an inconsistency remains unresolved, the harder it may be to reconstruct the history behind it.
Solution: Create a Centralized Fixed Asset Record
A strong fixed asset management process starts with one reliable source of asset information. Finance teams should define the information required when an asset is created and establish consistent procedures for subsequent transactions.
- Maintaining one authoritative asset record
- Standardizing required fields and classifications
- Recording acquisitions, transfers, adjustments, and disposals promptly
- Assigning responsibility for maintaining asset information
- Reconciling fixed asset records with the general ledger
- Performing periodic physical inventory where appropriate
- Preserving a traceable history of material changes
Dedicated fixed asset software can support these controls by maintaining asset records and related accounting activity in a centralized system rather than relying on separate spreadsheet versions.
For teams evaluating that transition, the features of fixed asset management software should be assessed against the transactions, reports, controls, and reconciliation processes the organization actually uses.
Challenge #2: Managing Depreciation Across Multiple Books
Depreciation becomes more complicated when the same asset needs to be accounted for differently depending on the reporting purpose. An organization may need separate schedules for financial reporting, federal tax, state tax, or other requirements. Those schedules can differ even though they relate to the same underlying asset.
Why Multi-Book Depreciation Gets Complicated
Different depreciation schedules may use different:
- Depreciation methods
- Recovery or useful lives
- Conventions
- Depreciable bases
- Tax treatments
- Reporting periods
Federal tax depreciation, for example, can involve MACRS, applicable conventions, Section 179 deductions, and special depreciation allowances. Financial reporting may use a different useful life or depreciation method.
The challenge is keeping the underlying asset information consistent while preserving the accounting rules that apply to each schedule. When each book is maintained separately in spreadsheets, even a simple change can require multiple updates.
Change an asset's placed-in-service information in one schedule but not another, and the records can begin to diverge.
Where Depreciation Errors Start
Many depreciation problems begin with the asset data rather than the calculation itself.
- Incorrect placed-in-service dates
- Incorrect asset classifications
- Inappropriate useful lives or recovery periods
- Wrong depreciation methods or conventions
- Adjustments made to one schedule but not another
- Disposals missing from one or more books
- Manual formulas that are changed or overwritten
These inconsistencies can become particularly visible during reconciliation. If depreciation expense in the fixed asset records does not reconcile with the amount posted to the general ledger, the accounting team must determine whether the difference came from the underlying asset data, the depreciation calculation, a transaction, or the posting process.
Solution: Standardize the Depreciation Process
Consistency is one of the most important fixed asset management best practices for depreciation. Finance teams should establish policies for how assets are classified, which depreciation schedules are required, how transactions are processed, and how depreciation is reviewed before posting.
- Maintaining consistent source data for each asset
- Keeping separate depreciation books where required
- Applying documented depreciation policies
- Reviewing unusual transactions and exceptions
- Recording disposals and transfers consistently
- Reconciling depreciation expense to the general ledger
- Retaining supporting documentation for significant changes
Dedicated fixed asset software can reduce dependence on separate spreadsheet calculations by applying depreciation methods to governed asset records and producing repeatable reporting.
Bassets eDepreciation supports commonly used depreciation methods and conventions, calculations for different periods, transfers and disposals, and general ledger workflows. See the Bassets eDepreciation platform for current product details.
Challenge #3: Keeping Tax Depreciation and Reporting Organized
Tax depreciation adds another layer of complexity because applicable rules can depend on the type of property, acquisition and placed-in-service dates, elections, depreciation method, recovery period, and current tax law. The accounting team therefore needs more than a depreciation total. It needs records that explain how that total was determined.
Why Tax Depreciation Requires Ongoing Attention
Federal tax treatment can involve MACRS depreciation, Section 179, special depreciation allowances, and rules governing capitalization and deductions. State treatment can also differ from federal treatment, creating additional schedules or adjustments.
Tax rules also change over time. IRS Publication 946 lists a maximum Section 179 expense deduction of $2.56 million for tax years beginning in 2026, with the limit reduced when qualifying property placed in service exceeds $4.09 million. The publication also describes the restored 100% special depreciation allowance for certain qualified property acquired and placed in service after January 19, 2025, subject to the applicable requirements.
That makes it important to evaluate an asset using the rules applicable to the relevant tax year rather than assuming that treatment used for an earlier acquisition remains appropriate.
Capitalization decisions also require context. Under the IRS de minimis safe harbor, qualifying taxpayers with an applicable financial statement may deduct amounts up to $5,000 per invoice or item, while qualifying taxpayers without an applicable financial statement may use a $2,500 threshold, subject to the election requirements and limitations.
Tax decisions should therefore be based on current guidance and the organization's specific circumstances.
Documentation Matters as Much as the Calculation
Reliable tax depreciation depends on preserving the information behind the calculation. Depending on the asset and applicable treatment, useful documentation may include:
- Original acquisition cost
- Placed-in-service date
- Depreciable basis
- Property classification
- Depreciation method and recovery period
- Applicable elections or special treatment
- Basis adjustments
- Transfer information
- Disposal date and proceeds where applicable
Maintaining these records makes it easier to reproduce calculations and provide support when preparing returns, reviewing prior periods, or responding to questions.
Solution: Build Tax Reporting Into the Fixed Asset Process
Tax depreciation should be supported throughout the asset lifecycle rather than treated as an isolated year-end exercise. Organizations should capture the information required for tax reporting as assets are acquired and transactions occur.
A more controlled process includes maintaining separate book and tax schedules where necessary, documenting adjustments and elections, reviewing current tax guidance, preserving supporting records, and reconciling depreciation information before tax reporting.
Reporting also matters. Finance and tax teams need to be able to move from individual asset records to depreciation detail, acquisitions, disposals, projections, and other supporting schedules.
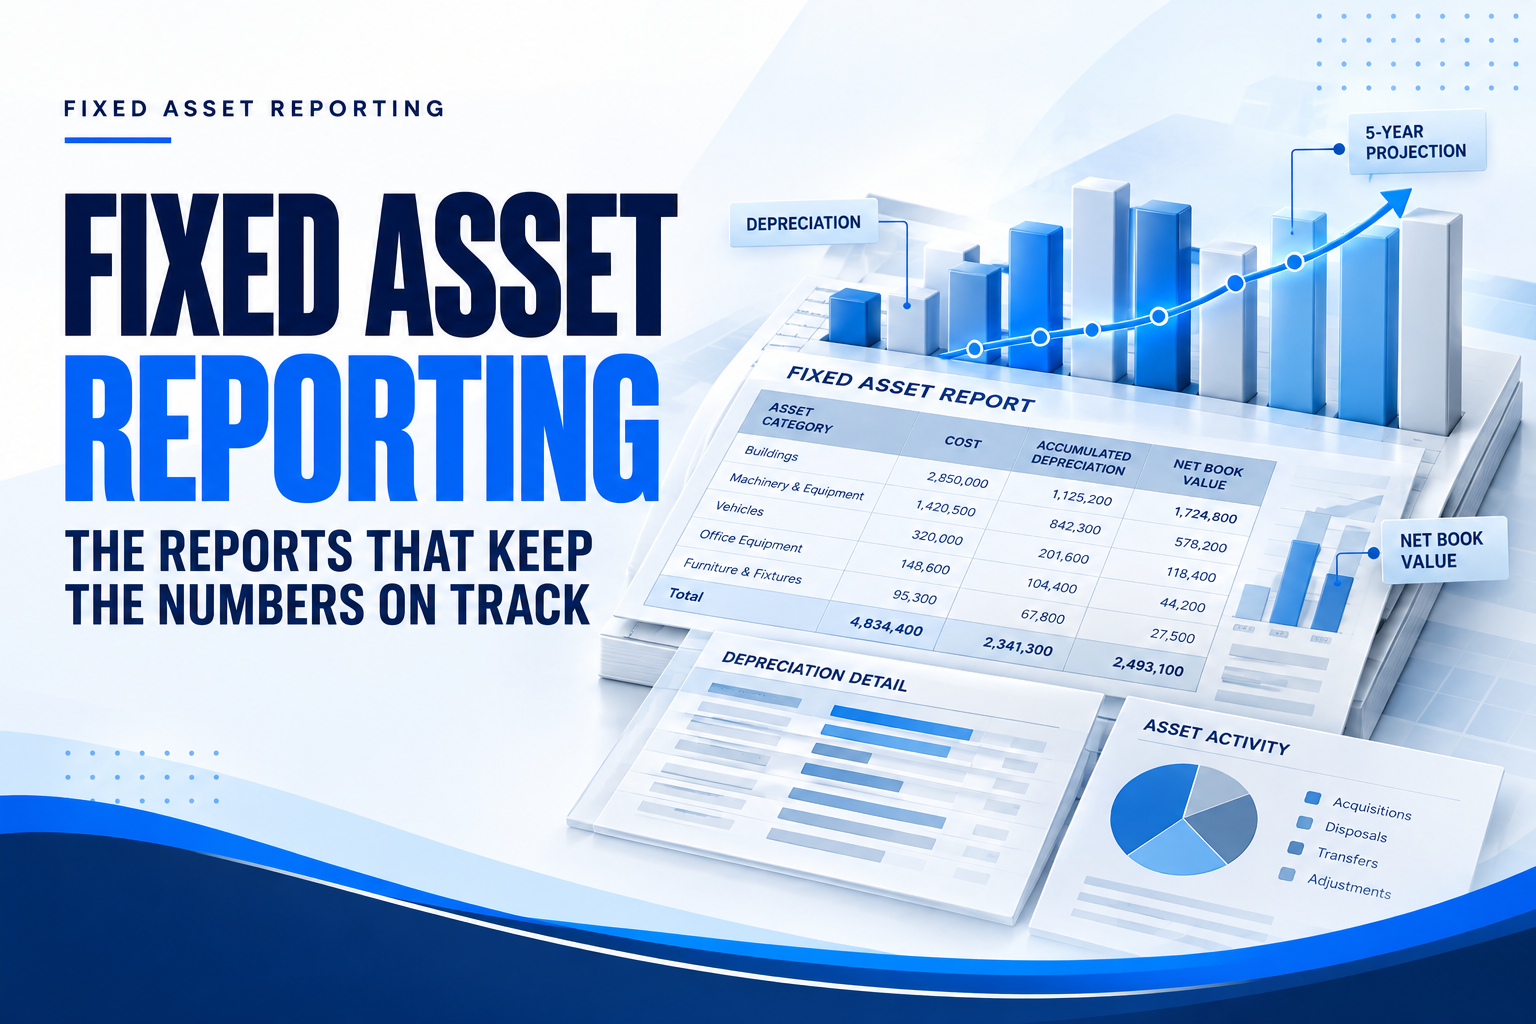
Bassets eDepreciation provides more than 20 standard reports, including depreciation detail, depreciation expense, asset acquisitions, asset disposals, inventory, transferred assets, and five-year depreciation projections. See Bassets fixed asset reporting for the current report set.
Software can support the calculation, recordkeeping, and reporting process, but tax positions and elections should still be evaluated based on applicable law and professional judgment.
Fixed Asset Management Best Practices
The best way to address fixed asset management challenges is to prevent inconsistencies from accumulating in the first place. These eight practices provide a practical foundation:
- Maintain one reliable asset record. Avoid competing files or schedules that make it unclear which information is current.
- Standardize data at acquisition. Capture required information such as cost, placed-in-service date, classification, location, and depreciation attributes consistently.
- Record transfers and disposals promptly. Asset records should reflect lifecycle changes when they occur.
- Maintain separate depreciation books when required. Preserve different accounting or tax treatments without duplicating the underlying asset unnecessarily.
- Reconcile fixed assets to the general ledger. Investigate differences rather than allowing them to carry into future periods.
- Perform periodic physical inventory. Compare recorded assets with what is actually in service where physical verification is appropriate.
- Maintain documentation and change history. Make significant transactions and adjustments traceable.
- Review the process as the portfolio grows. Controls and tools that work for a simple asset population may become difficult to maintain as locations, entities, users, and reporting requirements increase.
These practices strengthen the fixed asset management process regardless of which technology an organization uses.
Spreadsheet vs. Dedicated Fixed Asset Management
Spreadsheets and dedicated systems can both store fixed asset information, but they handle increasing accounting complexity differently.
The decision to move beyond spreadsheets should not depend on a universal asset-count threshold. A company with relatively few assets can still have a complicated process if it manages multiple entities, locations, depreciation books, or reporting requirements.
The better question is whether the existing process remains controlled, repeatable, and easy to reconcile.
When Is It Time to Improve Your Fixed Asset Management Process?
The need for a better process usually appears through recurring operational problems rather than a specific number of assets.
- Reconciliation regularly requires manual investigation
- Different teams maintain separate asset files
- Transfers and disposals are not recorded consistently
- Multiple depreciation schedules are difficult to reconcile
- Audit requests require reconstructing historical transactions
- Reports have to be rebuilt manually each period
- Physical inventory frequently disagrees with accounting records
- The process depends heavily on one person's spreadsheet knowledge
Start by identifying which problems come from the process itself. Standardizing responsibilities, data requirements, reconciliation, and transaction procedures may solve some issues. When the remaining problems come from maintaining calculations, books, transactions, and reporting across disconnected files, dedicated fixed asset software may provide a more sustainable foundation.
How Bassets Supports Fixed Asset Management
Bassets eDepreciation is designed to bring fixed asset accounting, depreciation, transactions, and reporting into a centralized system.
Current Bassets product information describes support for commonly used depreciation methods and conventions, calculations for different periods, complete and partial transfers and disposals, general ledger workflows, data validation, and fixed asset reporting. Bassets also offers Compact, Standard, and Enterprise editions for different portfolio sizes, with Enterprise supporting an unlimited number of fixed asset records.
For organizations that perform physical asset verification, Bassets also provides barcode inventory functionality that can compare imported barcode data with capital asset records.
The goal is to give finance teams a more controlled way to maintain the information behind depreciation, reconciliation, reporting, and asset lifecycle transactions.
Request a Bassets demo to see how eDepreciation handles fixed asset workflows using your organization's requirements.
Frequently Asked Questions
What are the most common fixed asset management challenges?
The most common fixed asset management challenges are maintaining accurate asset records, managing depreciation across multiple books, and keeping tax depreciation and reporting requirements organized. These problems often become more difficult as asset portfolios, locations, entities, and reporting requirements grow.
What are fixed asset management best practices?
Fixed asset management best practices include maintaining one authoritative asset record, standardizing asset data, recording transfers and disposals promptly, maintaining required depreciation books, reconciling fixed assets to the general ledger, performing periodic physical inventory, and preserving documentation and change history.
Why is fixed asset depreciation difficult to manage?
Fixed asset depreciation can become difficult because the same asset may require different methods, lives, conventions, bases, or tax treatments across financial and tax schedules. Inconsistent asset data or manual updates can then create differences between depreciation books and the general ledger.
How can businesses improve fixed asset data accuracy?
Businesses can improve fixed asset data accuracy by standardizing required fields, maintaining a centralized asset record, assigning responsibility for updates, recording lifecycle transactions consistently, reconciling records to the general ledger, and periodically comparing accounting records with physical assets.
When should a company move beyond spreadsheets for fixed asset management?
A company should consider moving beyond spreadsheets when its current process becomes difficult to control or reproduce. Warning signs include multiple asset files, recurring reconciliation problems, complicated depreciation schedules, inconsistent disposals, manual reporting, or difficulty reconstructing asset history for audits and tax work.